


Markets opened the week of 28 September 2026 with dearer oil, higher US Treasury yields and equity indices in decline. The move came amid diplomatic tension between the United States and Iran, not from a single closing statement.
Brent contracts briefly moved above $107 a barrel in the Asian session and at the open. Part of the gain later faded; midday prints and settlement prices are not the same. An intraday peak is not the closing price.
US bond yields rose. The 10-year note approached levels not seen in nearly two decades, according to that day’s market reports. Higher rates weigh on equity valuations independently of a barrel of oil.
US indices traded or closed lower: the Dow, S&P 500 and Nasdaq lost fractions of a percent. The drop describes one session, not an announced recession. Sector weights and the time of measurement change the reading.
Investors tied the oil jump to the stalemate over reopening the Strait of Hormuz and to the rejection of an Iranian proposal to halt hostilities. Headlines about talks restarting do not, by themselves, cancel supply risk.
Expected inflation and Federal Reserve policy stayed in the background. A dearer barrel can feed consumer prices, but a single day does not rewrite the path of rates. Data and FOMC decisions are read separately.
This text is not investment advice. Exact values come from commodity-exchange and Treasury settlements, not from a high in a news headline.
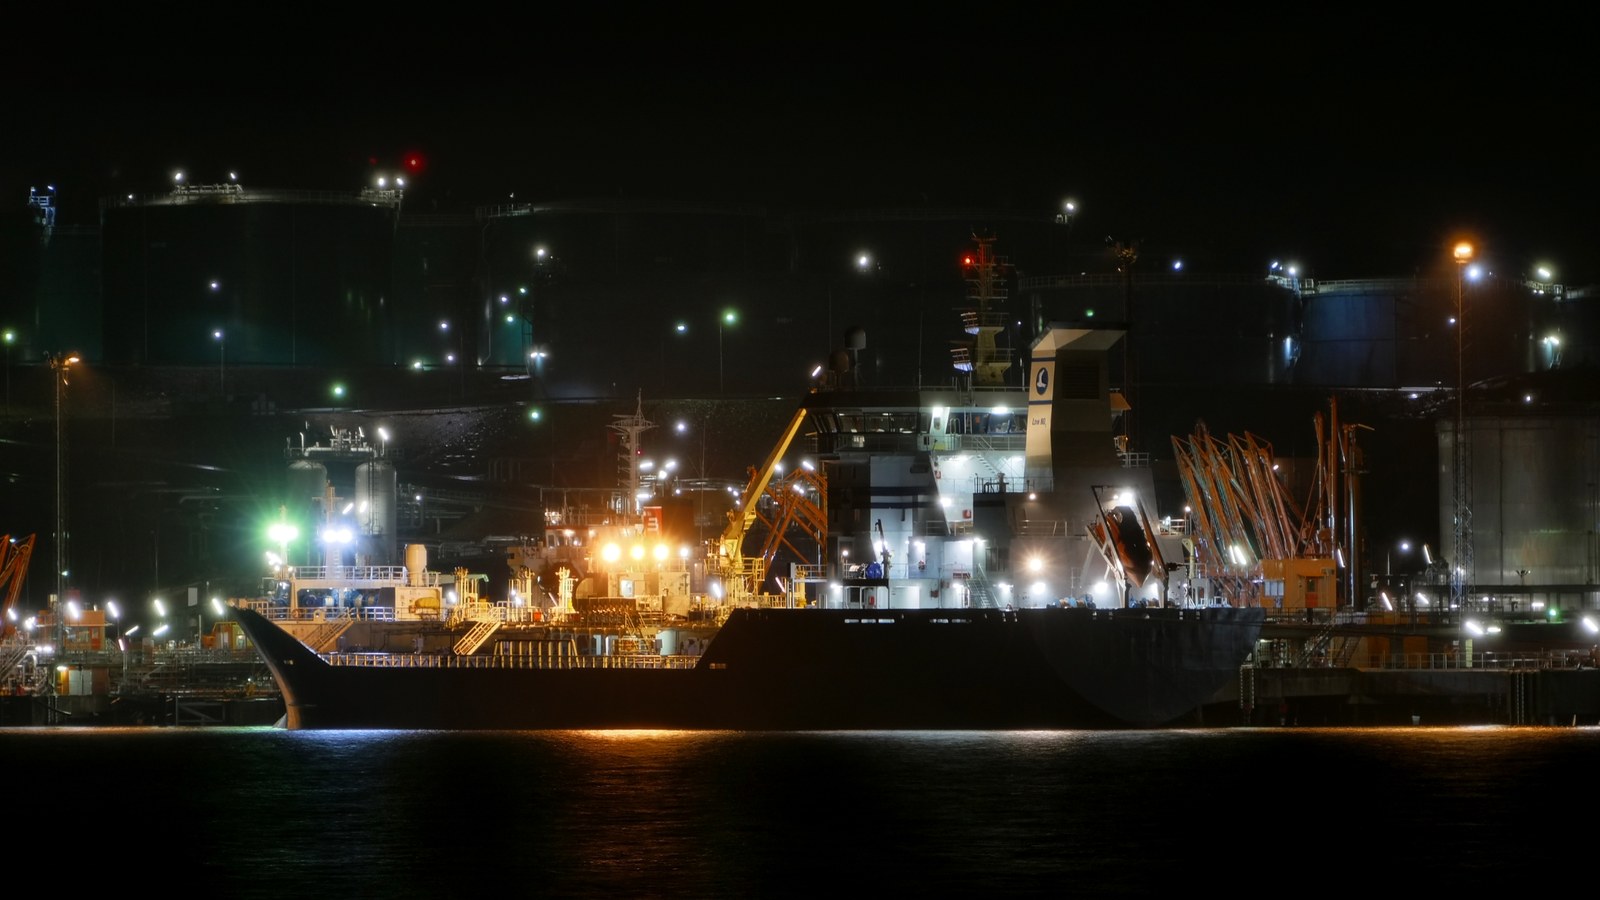
Image: W.carter, Preemraff Lysekil product terminal with tankers, 19 November 2016, CC BY-SA 4.0, Wikimedia Commons. A Swedish terminal, not Hormuz and not 28 September 2026. Cropped to 16:9.
Source consulted: Global Markets — Reuters.
0 Comments
No comments on this article yet. Be the first!