


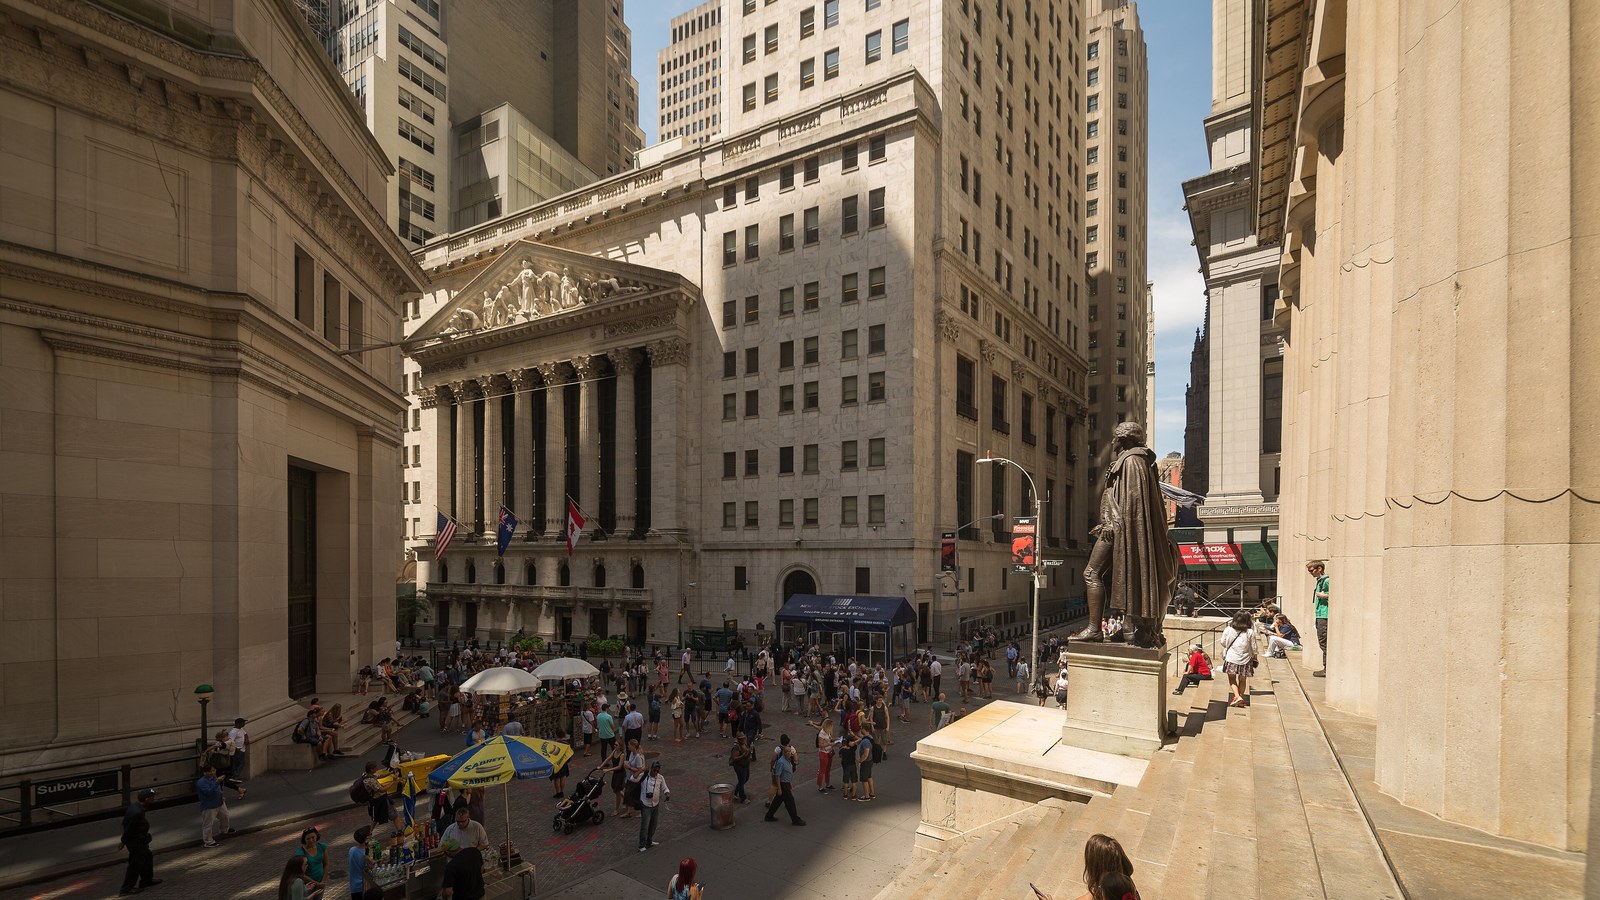
On 24 September 2026, global markets sat at the end of the third quarter, between appetite for AI-linked companies and the rising cost of finance. Reuters’ “Take Five” of 25 September described that balance as tense, not as a finished trend.
Major equity indexes were, according to the same round-up, less than 2% off record highs and more than 12% higher on the year, largely on AI euphoria. Bonds told another story: global borrowing costs were described as their highest since the 2007–08 crash.
Rate markets were pricing a faster tightening cycle than a few weeks earlier. Ten-year US Treasury yields had moved above 5%, a level many newer investors have not treated as a lasting norm.
Energy volatility entered the same equation: if higher energy prices persist, they may push wages, living costs and interest rates. One session does not set the path. The indicators that follow remain inflation, employment and central-bank signals.
Reuters flagged the US jobs report, the PCE index and euro-zone inflation as tests for rate expectations. Micron’s results, from a supplier of memory for AI data centres, were presented as a test of infrastructure spending, not a verdict on the whole sector.
Technology optimism and yield pressure can coexist for days. This article does not turn a market comment into a forecast and does not attribute unannounced decisions to central banks.
Image: New York Stock Exchange, August 2017 / Arild Vågen, Wikimedia Commons, CC BY-SA 4.0. The exchange façade, not the 24 September 2026 session. Cropped to 16:9.
Source consulted: Take Five: global markets themes graphic | Reuters; Graphic: Take Five - It's Q4 already | DevDiscourse (Reuters syndicate).
0 Comments
No comments on this article yet. Be the first!