


United Airlines Holdings reported third-quarter results on Tuesday, 20 October 2026, for the period ended 30 September. GAAP net income was $1.029 billion, or $3.14 per diluted share, compared with $949 million, or $2.90, in the same quarter of 2025. The 8.5% rise in net income is a quarterly earnings print, not a bankruptcy filing and not a collapse of the airline.
Total operating revenue was $17.875 billion, up 17.4% from $15.225 billion a year earlier. The company called the revenue figure an all-time record. Capacity, measured in available seat miles, rose only 1.3%. United carried 49.5 million passengers in the quarter, 2.4% more than in the third quarter of 2025.
Excluding special items, adjusted net income was $833 million, or $2.54 per share. On the same basis a year earlier the figures were $909 million and $2.78: an 8.4% drop in adjusted profit and an 8.6% drop in adjusted earnings per share. The two series should not be mixed. The company said the adjusted result sat inside the July guidance range of $2.50 to $3.50 for the third quarter. LSEG estimates cited by CNBC were $2.57 per share and $17.9 billion of revenue.
The fuel bill rose to $4.843 billion from $2.997 billion, up 61.6%. The average price paid in the third quarter was $3.90 a gallon. The release puts the year-on-year increase in fuel expense at $1.8 billion. That is why the margin is under pressure even with demand holding: revenue grew, and cost per available seat mile also rose, by 17.3%.
In the 20 October investor update, United estimates fourth-quarter adjusted earnings of $0.50 to $1.50 a share. That is guidance, not a result already booked. CNBC, again citing LSEG, said analysts had expected $1.76. For fuel, the company assumes about $4.80 a gallon in the fourth quarter, based on the Gulf Coast jet forward curve as of 16 October; that is a working assumption, not a price already paid. In the same table, the full-year 2026 column for adjusted earnings per share is left blank: United did not publish a new annual range on Tuesday.
On 15 July the investor update still pointed to $9 to $11 a share for the full year 2026. CNBC calculates that if the fourth quarter hits the $1.50 high end, full-year adjusted earnings would come to no more than $7.22 — $5.72 for the first nine months plus $1.50. The $7.22 figure is press arithmetic, not a new target written by the company.
Chief executive Scott Kirby said in the release that employees had met the challenge of an ever-changing environment and that the results show the resilience of building a brand-loyal airline. The company expects fourth-quarter operating revenue to rise by more than 20% year on year; that too is an outlook, not a booked figure. The analyst call is set for Wednesday, 21 October, at 9:30 a.m. Chicago time; at the time this article was published there was no transcript.
Available liquidity at 30 September was $17.7 billion. Total debt, finance-lease obligations and other financial liabilities were $26.4 billion. Trailing twelve-month net leverage was 2.4 times. Pre-tax profit was $1.3 billion (7.3% margin); on an adjusted basis, $1.1 billion (6.2% margin).
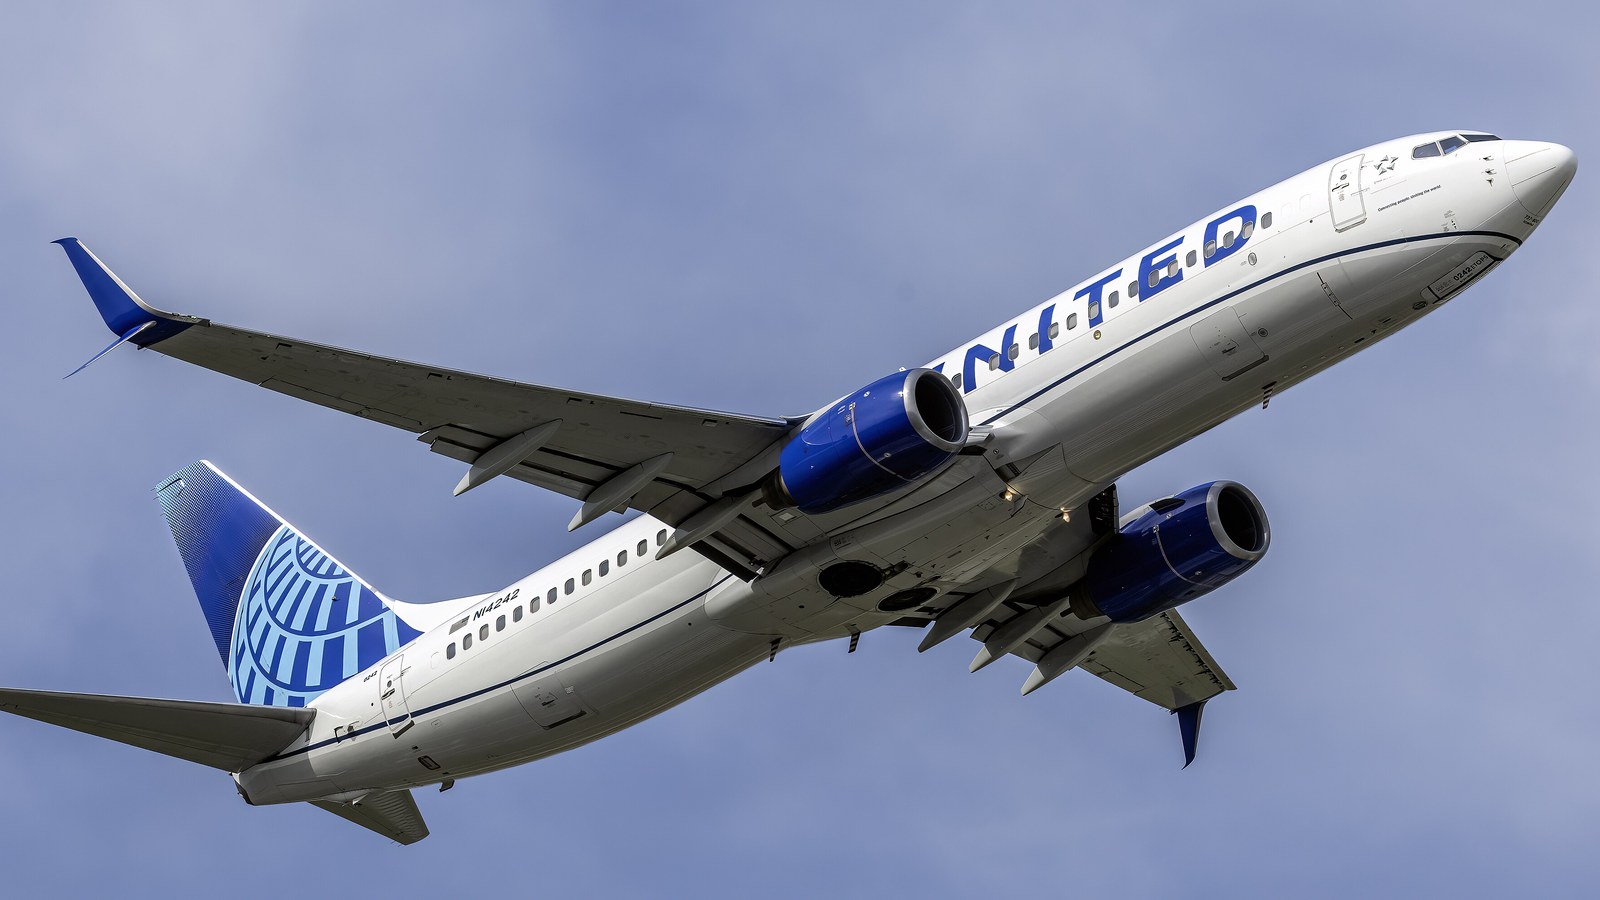
Image: United Boeing 737-800 N14242 taking off at Baltimore-Washington International Airport, 24 April 2025, Acroterion, CC BY-SA 4.0, Wikimedia Commons. The aircraft, not an earnings studio.
Sources consulted: United Airlines slashes 2026 profit outlook on fuel prices, but travelers keep booking despite higher fares — CNBC; United Delivers Record 17% Revenue Growth in Q3, and Expects Record Q4 Revenue Growth, Underpinned by Accelerating Customer Investments — United Airlines; Investor Update, 20 October 2026 — United Airlines Holdings.
0 Comments
No comments on this article yet. Be the first!