


On 5 February 2014, at Ottawa, Canada and the United States signed the Agreement to Improve International Tax Compliance through Enhanced Exchange of Information under the 1980 Convention with Respect to Taxes on Income and on Capital. Done in duplicate; authentic texts: English and French. It is a reciprocal Model 1 intergovernmental agreement, distinct from the 2010 U.S. FATCA statute and from the tax convention of 26 September 1980, whose Article XXVII authorises exchange of information, including on an automatic basis.
Canada's Department of Finance announced the signature: Finance Minister Jim Flaherty and National Revenue Minister Kerry-Lynne D. Findlay. Competent authorities: for Canada, the Minister of National Revenue or an authorised representative; for the United States, the Secretary of the Treasury or delegate. Canadian financial institutions report to the Canada Revenue Agency, not directly to the Internal Revenue Service; the Agency then exchanges the information with the IRS under the Convention.
Article 2: each Party obtains and exchanges annually information on reportable accounts — identity, account number, institution, balance and, on a phased basis, income. Article 3: amounts may be characterised under the reporting Party's tax law; exchange within nine months after the end of the calendar year. The entry-into-force notice: reciprocal exchange was to begin by the end of September 2015. Annex I sets due-diligence rules; this article does not treat them as an operations manual.
Article 4: Reporting Canadian Financial Institutions are treated as complying with FATCA; the 30 percent withholding does not apply to their clients, and can apply to an institution only if it is in significant, long-term non-compliance. Annex II, as confirmed in the Finance release: registered plans — RRSPs, RRIFs, RDSPs, TFSAs — are not reportable; smaller deposit-taking institutions such as credit unions with assets under USD 175 million are exempt.
Article 10: the Agreement enters into force on the date of Canada's written notification that internal procedures are complete. Finance Canada: 27 June 2014. Part 5 of Bill C-31 received Royal Assent on 19 June 2014; the provisions generally have effect from 1 July 2014. Article 10(2): either Party may terminate on written notice, effective the first day of the month after 12 months. Article 7: Canada receives the benefit of more favourable Article 4 or Annex I terms granted to another Partner Jurisdiction that undertakes the same obligations.
The U.S. Treasury published the text the same day, together with other Model 1 agreements. The consultations in Article 10(3), before 31 December 2016, concerned the Article 6 commitments on equivalent levels of exchange and common reporting standards, not a separate treaty. The later OECD Common Reporting Standard is a distinct instrument.
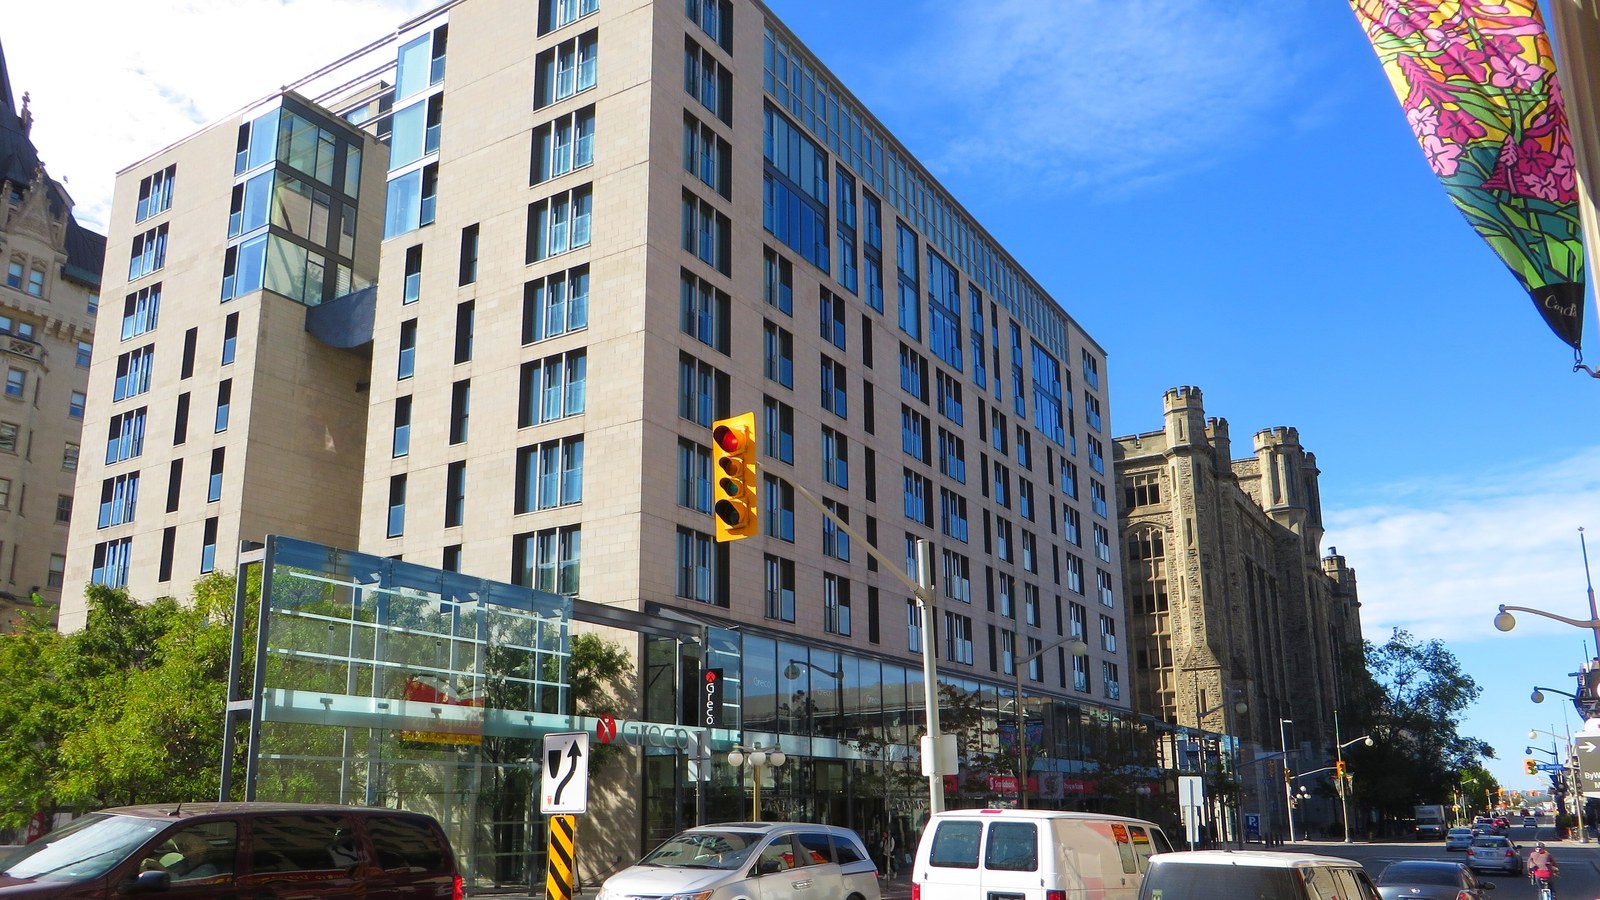
Cover: the Connaught Building in Ottawa, national headquarters of the Canada Revenue Agency, the Canadian channel in Article 2 — not the signing room. Wikimedia Commons, free licence.
For context: FATCA agreement between Canada and the United States. The text: Agreement between the United States and Canada to Improve International Tax Compliance.
0 Comments
No comments on this article yet. Be the first!