
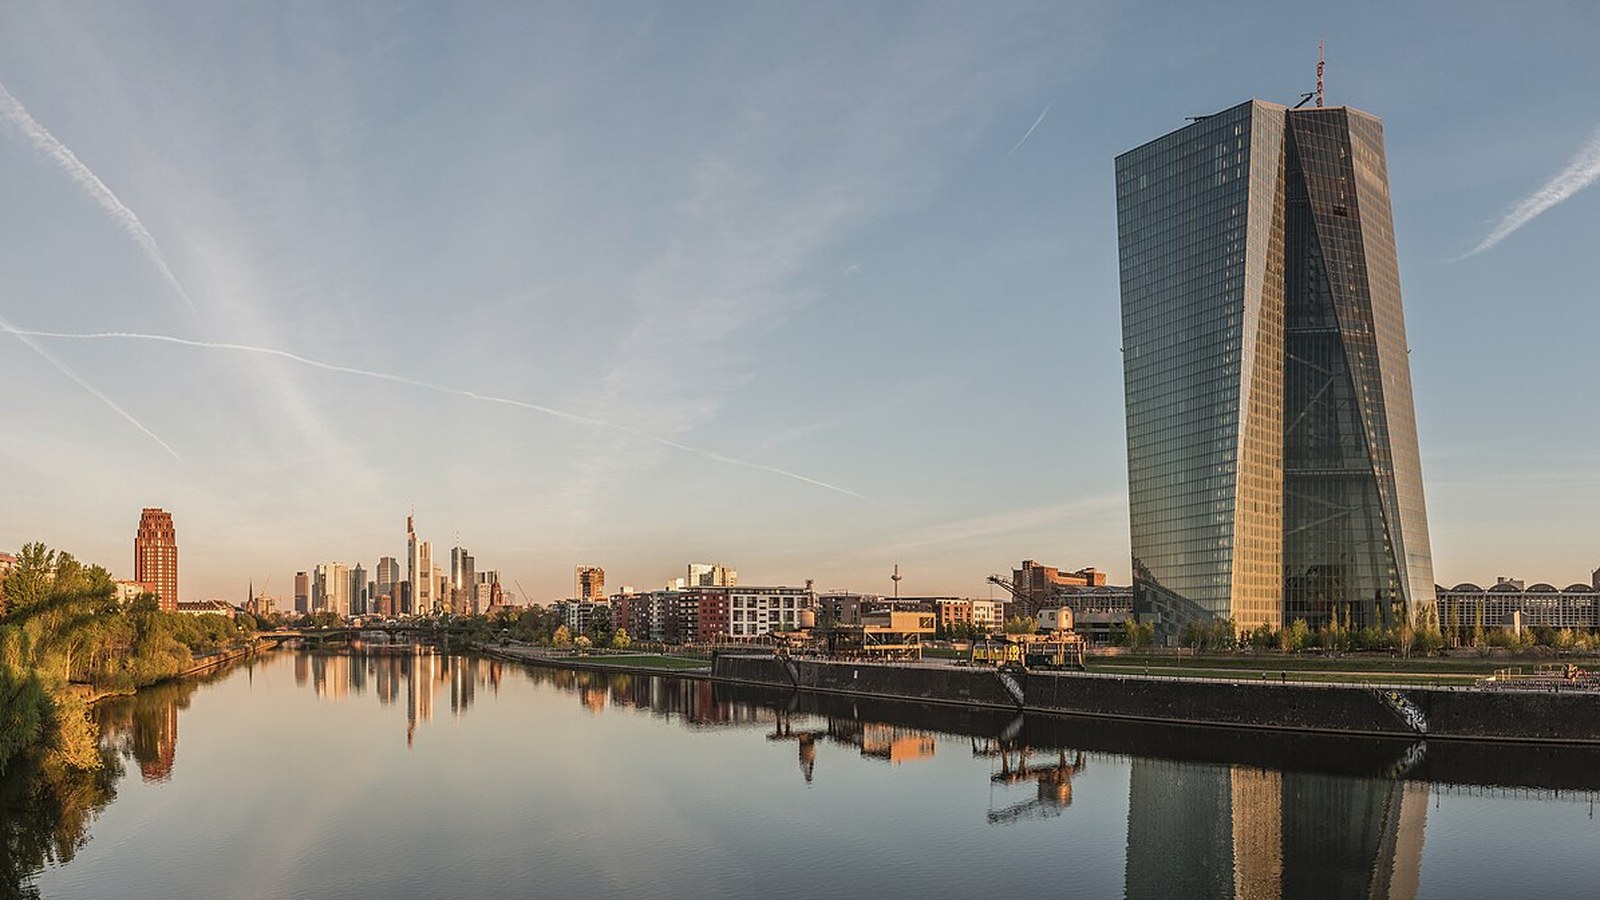
The European Central Bank’s new interest rates take effect today, 16 September 2026, following the Governing Council’s decision to raise all three key rates by 25 basis points.
The deposit facility rate rises to 2.50%, the main refinancing operations rate to 2.65%, and the marginal lending facility rate to 2.90%.
The decision was taken on 10 September, with the ECB explicitly setting 16 September as the effective date.
The increase comes as the central bank judges that inflationary pressures will remain elevated for an extended period. The ECB’s medium-term objective is to stabilise inflation at 2%.
New staff projections put headline inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028. Inflation excluding energy and food is projected at 2.5%, 2.6% and 2.3% respectively.
Compared with June’s projections, the 2026 inflation forecast is unchanged, while 2027 and 2028 have been revised upwards.
The ECB links current pressures in part to the conflict in the Middle East and its effect on prices. That is the ECB’s official assessment and should be attributed to the institution rather than presented as the only possible cause of inflation.
The central bank also revised its growth outlook. The baseline sees euro-area growth of 0.9% in 2026, 1.4% in 2027 and 1.5% in 2028.
The ECB says the upward revisions for 2026 and 2027 mainly reflect greater-than-expected resilience in the euro-area economy.
Higher policy rates affect the economy through financing conditions, but the effects do not appear identically or instantly in every contract.
Mortgage rates, business loans, deposits and other products also depend on contract structure, local markets, customer risk and individual bank policy.
It would therefore be wrong to say every borrowing rate automatically rises today by exactly 0.25 percentage points. Monetary-policy transmission is gradual and differs across products and countries.
The ECB also says its Asset Purchase Programme and Pandemic Emergency Purchase Programme portfolios continue to decline at a measured and predictable pace because the Eurosystem is no longer reinvesting principal payments from maturing securities.
The Governing Council says it stands ready to adjust instruments to return inflation to 2%, but future decisions are not predetermined.
The current increase should therefore not be presented as a guaranteed start to a series of further rises.
For Romania, which is outside the euro area, ECB rates are not the National Bank of Romania’s monetary-policy rates. Nevertheless, euro-area developments matter through trade, financing, exchange rates, investment and banking links.
For countries using the euro, the change applies directly to the monetary framework.
From today, the three key levels are 2.50%, 2.65% and 2.90% — the ECB’s current response to inflation it expects to remain above target in an uncertain economic and geopolitical environment.
Image: Daniel Vorndran (DXR) / Wikimedia Commons, CC BY-SA 4.0. ECB headquarters and Frankfurt skyline, 22 April 2015. Cropped to 16:9.
Source consulted: Monetary policy decisions, 10 September 2026 | European Central Bank; Decizii de politică monetară, 10 septembrie 2026 | Banca Centrală Europeană.
0 Comments
No comments on this article yet. Be the first!